As crazy as it sounds, you could be better off in retirement than in employment.
In some circumstances, your occupational, personal and state pension funds could provide you with sufficient income and capital to retire now.
A UK law passed in 2015 gives individuals more freedom around how they use and access their pension pots, whether they be a defined benefit (DB) scheme (also known as final salary schemes) or a defined contribution scheme. This means there are more possibilities open to you rather than just waiting to reach retirement age.
Flexible access to your pension funds could open up new ways of thinking about retirement for you. A qualified Financial Adviser can guide you through the options, taking into account your personal circumstances, and find the most suitable and appropriate solution for you.
Curious to know more?
Besides freedom of choice, here's why you might look at other options:
You can access cash when you need it most
A DB pension will offer a guaranteed income for life with minimal risk. Whilst these benefits can be very valuable and attractive, for some people they can also be rather rigid and inflexible.
For example, a DB scheme may have a set retirement age and although taking the pension benefits earlier than this date may be possible, it may not be on favourable terms. In this case, taking the pension earlier than the normal retirement age may mean the income is much lower than if you had waited until you reached the normal pension age.
Consequently, many people are choosing to have flexible access to their pension funds sooner rather than later, so that they can fulfil their dreams: for example, retiring earlier than they had originally intended or before the state pension age.
Flexible access means that you get to decide how you wish to spread your income and spending through your retirement, rather than having a rigid amount throughout. For example, you may take the view that you want to spend more in earlier retirement while you are more mobile and able to travel and spend less later in retirement.
By transferring your DB scheme into a personal pension, your funds will then be invested in funds suitable for your agreed level of investment risk. Investments can go down as well as up and this is a risk which we will help you to understand, but sadly we can never eradicate it. It’s important to take advice throughout retirement to monitor the impact of your withdrawals on your pension, to ensure the fund isn’t depleted during your lifetime
Whilst it’s important to have a nest egg, it’s also important that it fits into and works alongside your own situation and goals.
Higher than average transfer values mean that now is a good time
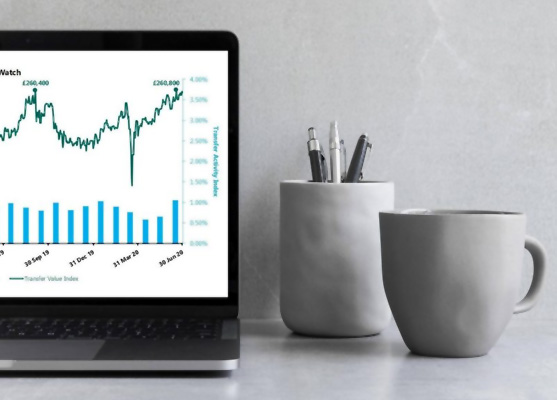
A DB pension is effectively a deferred annuity and as the costs of annuities have soared with the fall in returns from low risk investments, as well as rising life expectancy, so has the transfer values of transferring out of these DB schemes.
The recent market uncertainty has resulted in the yields of investments such as Government Bonds decreasing, which has a negative correlation with transfer values, resulting in the average transfer values increasing significantly during 2020.
If you move away from the guaranteed returns and minimal risk of a DB pension, then the larger your pension pot is, the more it can provide you with increased capacity for loss in the event of an unexpected downturn in the investment markets. It’s important to carefully consider any decisions in respect of your pension, to ensure you fully understand the implications and you are not unduly influenced by a large transfer value.
There could well be tax savings
Accessing your pension fund flexibly could be more tax efficient.
You can almost always save on the tax associated with a DB pension. This may include:
- A higher tax-free cash lump sum
- Limiting your pension income to remain within the basic rate tax bracket
- Deferring withdrawals to pass on pension funds to future generations (your pension is normally free of inheritance tax)
That’s potentially less tax to pay the taxman and more money in your pocket.
Your spouse might only get half if you die
In many DB schemes, surviving partners may only be entitled to half the income that you would receive.
In some instances, remaining in traditional DB schemes means you cannot ensure your spouse will be financially taken care of in the event of your death.
By accessing your pension scheme flexibly and in a sustainable manner 100% of any remaining funds can be transferred to your heirs and successors (dependent on individual circumstances and age; may be subject to tax at recipient’s marginal rate; and provided that the investments have performed as planned).
Schemes can differ, so I would always advise anyone with a DB scheme to clarify for themselves what would happen in certain instances.
Your kids might get nothing if you die
Although most schemes include benefits for your dependent children if something happens to you, once these children become adults and financially independent of you then the majority of schemes will offer little to no benefits to your children on your death.
Again, by accessing your funds in a flexible manner, it would allow your children (of any age), and indeed any of your successors and heirs, to access all of the remaining pension funds after your death.
Is a defined benefit transfer right for me?
For some people, the arguments in favour of transferring may be particularly compelling. Those who want to maximise their tax-free cash, do not expect to live long in retirement, are thinking about how best to pass on unspent pension to their heirs, are willing and able to take on the investment risk associated with their pension could all find that there are compelling reasons to consider a transfer.
On the other hand, those who value the certainty which a DB pension provides may well wish to stay put.
If they do so, they will know that their pension will last as long as they do, that they have a measure of insulation against inflation, that they do not need to worry about the ups and downs of the financial markets and that there will be a pension there for a widow or widower when they are gone.
Every person’s circumstances are different and one of our expert Pension Transfer Specialists can advise if it’s in your best interest to transfer.
Real Life Examples
£21,000 a year when you retire or £758,000 today?*
Mike is 55 and lives with his wife in London. His final salary pension entitled him to £21,000 a year from age 55. When Mike requested his pension transfer value, he was offered £758,000.
Mike’s aim was financial security for himself and his family with the flexibility to access his pension as he wishes.
By transferring the pension, he received a larger element of tax-free cash and can maintain his income in retirement. Mike’s children will now inherit the remainder of his pension following his death.
£18,000 a year on retirement, or £448,000 today?*
Emily is 40 years old, single and lives on her own in Leeds. She is concerned that if she were to die, her pension fund would not provide any death benefits, and she would like her parents to benefit.
Emily intends to retire at age 67 and isn’t sure what she will need in retirement as it is so far in the future.
Remaining in her Final Salary scheme is the best solution for Emily, as she is uncertain of her future needs and she could secure death benefits through life assurance if required.
* based on an individual circumstance and may not apply to every situation.
Paul Raper is a Restricted Financial Adviser within True Potential Wealth Management. True Potential Wealth Management is a Limited Liability Partnership, OC356611, and is authorised and regulated by the Financial Conduct Authority. FNR Number 529810. Registered Head Office: Newburn House, Gateway West, Newburn Riverside, Newcastle upon Tyne, NE15 8NX
Please be aware that this communication should not be considered as financial advice. Tax rules can change at any time. Please remember that a transfer out of a defined benefit scheme is an irrevocable complex transfer.
Contact Details
T: 01759 487577
M: 07919 440460
E: paulraper@tpllp.com
Please click here for more info about myself, Paul Raper.
 Powered by Majestic3.com